You want to know what to set aside for taxes, but your books are three months behind. Revenue feels strong. The bank balance looks healthy. Neither tells your CPA enough about how the year is actually going.
A useful tax-planning conversation starts with a financial picture you can explain. When transactions are missing or unclear, the first task becomes reconstructing the past. That leaves less time to discuss decisions ahead.
Current books give the conversation a starting point
In our Your Business Numbers series, we explained why accurate books are only the beginning. Reports become useful when they help you understand what is happening and decide what to do next. Tax planning is one practical use of that information.
Your CPA needs to know which period the reports cover, whether bank and credit card accounts have been reconciled, and what remains unresolved. Reconciliation means checking the books against account statements and explaining differences. A report labeled “year to date” can be misleading if recent activity has not been entered or reviewed.
The IRS describes good records as a foundation for financial statements and monitoring business progress. For planning, those records also give you and your CPA a shared starting point for discussing expected results.
A bank balance cannot answer the tax question
Suppose your consulting practice has a stronger cash balance than last year. Before treating that as money available for an owner distribution or a major purchase, you need to understand what is behind it. What obligations are coming due? Is recent activity fully recorded? Does the balance reflect normal operations or something unusual?
Your profit and loss statement and balance sheet help frame those questions. Your CPA then considers how the accounting results relate to your tax situation. Reported profit is not automatically taxable income, and cash available today is not a tax projection.
Payroll, owner distributions, and equipment purchases also need clear records so your CPA can evaluate their treatment. They should not be grouped together simply because each moves money out of the bank. The appropriate treatment depends on the transaction and your business circumstances.
Reliable information makes estimates more useful
Planning still involves assumptions. Current books cannot tell you exactly what the rest of the year will bring, but they help distinguish recorded results from expectations.
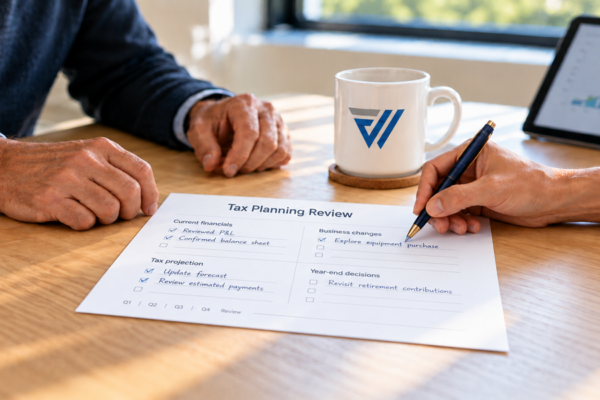
Bring your CPA the latest reviewed financial reports, a note about unresolved items, and your expectations for the remaining months. Discuss upcoming payroll commitments, purchases, and owner withdrawals before committing the cash. If the books are behind, ask what needs to be brought current first; you do not have to postpone the initial conversation until everything is perfect.
Changes in expected income may also warrant reviewing estimated tax payments. The IRS explains how estimates can be recalculated when expectations change. Your CPA can determine what applies to you.
Ask one practical question: “Are these numbers current and reliable enough for us to plan from?” Woodard & Associates CPA helps connect ongoing bookkeeping, financial review, and tax planning so that conversation can happen while decisions are still ahead.
Once the numbers are reliable, the next question is what changed in your business this year. That is the focus of our next article.