The year ends. You gather your records, send them to your CPA, and wait to learn what the tax return shows. That process is important: the return reports the year that actually happened. But if it is your first substantial tax conversation with your CPA, much of the year is already beyond your control.
Tax preparation and tax planning answer different questions. Preparation asks, “How do we report what happened?” Planning asks, “Given what we know now, what decisions are coming, and what should we consider before making them?”
The conversation changes when it happens earlier
Your business does not make all its decisions during tax season. You may hire, change compensation, buy equipment, take on a new line of work, or consider a change in ownership. Each decision has a business reason. Some may also have tax consequences that are easier to evaluate before you commit.
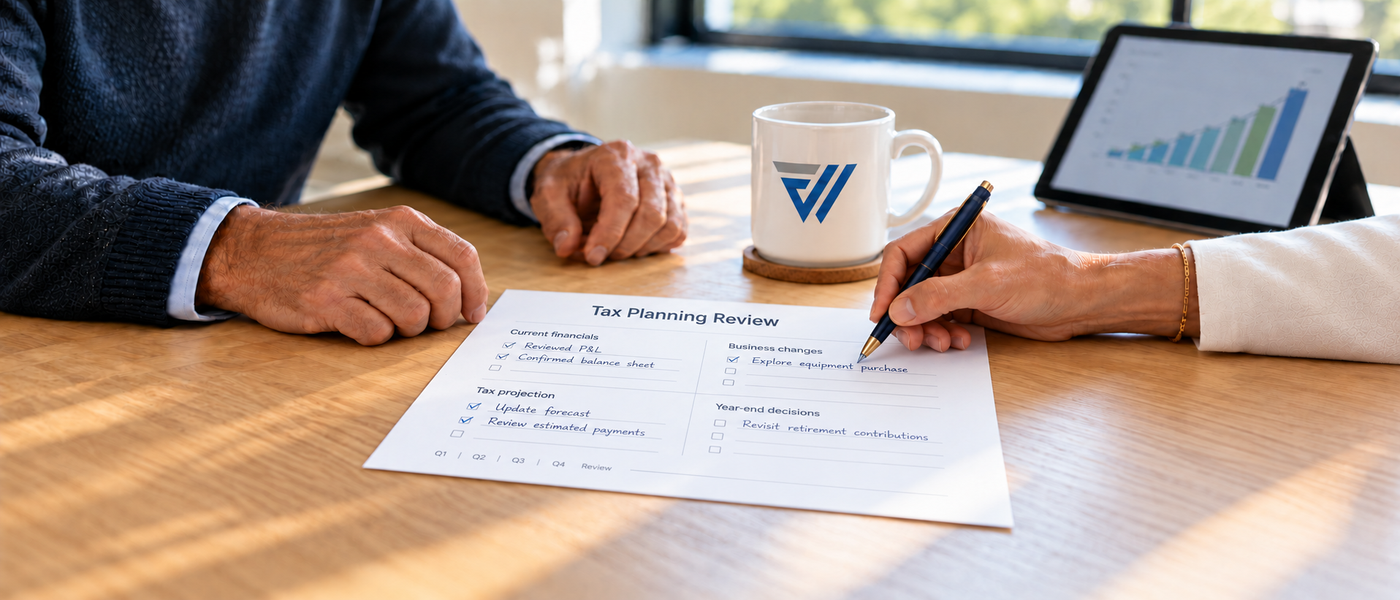
Suppose you are considering a substantial equipment purchase. Your CPA can discuss the possible tax treatment, but the purchase still needs to make sense for your operations and cash flow. A conversation after the purchase may help you report it correctly. A conversation beforehand can also help you weigh the timing and the broader financial tradeoffs. The answer depends on your circumstances; a tax benefit alone is not a reason to spend money.
The IRS encourages year-round tax planning, including keeping records current and responding to changes during the year. Planning is not a promise that you will owe less. It can help you understand likely obligations, set aside cash, and make decisions with a clearer view of their consequences.
Good planning uses the information available now
You do not need a perfect forecast before talking with your CPA. You do need a useful picture of where the business stands and what may change. Current financial reports, expected income, upcoming commitments, and questions about major decisions give the conversation something concrete to work from.
For some businesses and owners, changes in expected income may also mean revisiting estimated tax payments. The IRS explains that estimated taxes are based on expected income and may need to be recalculated as expectations change. Your CPA can assess whether that applies to you and how it fits your cash plans.
This is where your books matter. If the numbers are incomplete or months behind, it is harder to identify changes early or estimate what the rest of the year may look like. Reliable records and useful reporting support a better planning conversation. Our next article, Good Tax Planning Starts With Good Numbers, will look more closely at that foundation.
Make tax season the end of the conversation, not the beginning
A year-round relationship does not require a constant search for tax strategies. It means your CPA understands the business well enough to ask timely questions: What changed? What decisions are ahead? Do the current numbers suggest an issue worth examining? What should you prepare for before year-end?
Start by bringing your CPA one upcoming decision and your most recent financial information. Ask whether there are tax considerations to discuss before the decision is final. Woodard & Associates CPA helps business owners connect those conversations with accounting, tax planning, and broader business goals throughout the year.
Tax season should ideally bring together the records and decisions already discussed, rather than be the first time you learn what the year meant for your taxes.