You have enough work to consider another employee. The equipment you have been putting off would make the business easier to run. Or a larger space has become available, and the timing feels right.
The opportunity may make sense. The harder question is whether your business can support the commitment without putting too much pressure on everything else.
A healthy bank balance or a profitable year can make you feel ready. Neither tells you, on its own, what will happen after you commit. You need to understand the full cost, when cash will leave the business, when the expected benefit will arrive, and how much room remains if the plan takes longer than expected.
This is where reliable financial information becomes useful decision support. A CPA/accounting partner who knows your business can help you evaluate those questions before the offer is made or the agreement is signed.
Start with what the business already needs
Before deciding what you can add, look at the commitments you already carry.
Your bank balance may include money that will soon be needed for payroll, vendor payments, taxes, debt payments, or work you have promised to deliver. Recent collections may have made cash look unusually strong. A seasonal slowdown may be approaching even though the last few months were busy.
The starting point is a current picture of expected receipts and payments, including obligations that do not fall neatly into the monthly profit number. Your accountant can help connect those amounts to your records and identify gaps before they become assumptions in a forecast.
That depends on books you can trust and reporting that reflects how your business operates. If the reports are late or significant items still need explanation, the decision may need better information before it needs a yes or no.
Look beyond the headline price
A salary, purchase price, or monthly payment is a starting point for the conversation. The commitment usually has more parts.
For a new employee, consider applicable employer payroll taxes, benefits, recruiting, training, equipment, and the time other people will spend helping the person become productive. An equipment purchase may bring installation, maintenance, insurance, and training costs. More space may require deposits and improvements before it supports additional business.
Separate the costs paid at the beginning from those that will continue. Then ask what the decision is expected to change: more capacity, fewer delays, lower operating costs, better service, or time you can redirect to other work. The SBA's business finance guidance provides a useful starting point for comparing costs and benefits. For a significant commitment, your own operating history and assumptions need to fill in the details.
The benefit does not always have to be immediate revenue. But it should be clear enough to discuss and, where possible, evaluate after the decision.
Test the months before the benefit arrives
Consider a hypothetical service business evaluating another employee. The existing team is stretched, and a new hire could help take on more work. Payroll would begin right away. Training would take time, and clients would pay after the work was completed and billed.
An annual estimate might suggest the hire is worthwhile while overlooking pressure in the first few months. The useful question is whether the business can carry those months alongside its existing obligations.
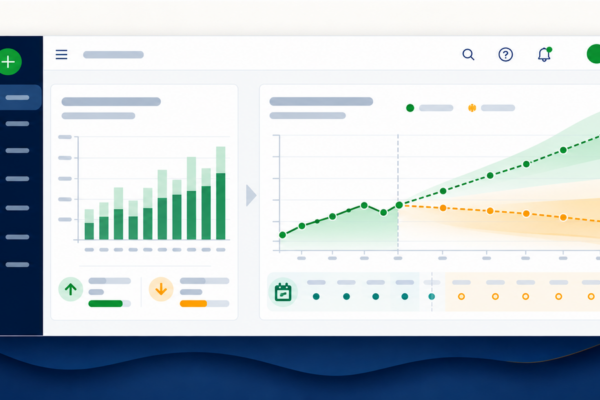
With your CPA/accounting partner, compare the expected case with a slower case. What if the employee takes longer to reach the expected workload? What if a project starts late or an important customer pays more slowly? Also consider what happens if you wait: capacity constraints can have a cost, too.
Follow the projected cash balance through the period when the decision creates pressure. Pay attention to its lowest point and the cash cushion left for ordinary uncertainty. The cushion should reflect your business's payroll cycle, collection patterns, seasonality, and other commitments. A generic reserve target cannot settle that judgment for you.
This comparison can lead to a more useful answer than a simple yes or no. You might proceed now, change the start date, reduce the initial commitment, or wait until a specific contract or collection is confirmed.
Evaluate financing and taxes within the same decision
Financing can change when cash leaves the business, but it adds a repayment commitment. Evaluate the proposed payment schedule, interest, fees, and other terms alongside the cash the business expects to generate. If the plan depends on borrowing, confirm the available terms before treating the funding as part of the decision. Your CPA can help assess the financial effect; your lender and attorney can address financing terms and legal obligations within their roles.
Tax treatment also deserves attention before you commit. A deduction reduces taxable income; it does not reimburse the purchase price. For equipment, the timing and amount of deductions depend on the applicable rules and the facts of the purchase and use. The IRS guidance on depreciating business property explains why eligibility and when property is ready and available for its intended use matter.
Ask your CPA to evaluate the expected tax effect and when any benefit would affect cash. A possible future tax benefit should not be treated as money available to cover today's payment. The business purpose, ongoing cost, and cash requirements still need to work together.
Bring a concrete decision to the conversation
You do not need to build a detailed financial model before asking for help. Bring the proposal, the expected timing, and the assumptions behind it. A productive discussion should answer a few questions:
- What will we commit to upfront and over time, including related costs?
- What needs to happen for the expected benefit to arrive, and what evidence supports that expectation?
- How much cash remains at the tightest point if results or collections are slower?
- What would make us change the timing, scope, or decision?
- If we proceed, when will we compare actual results with the assumptions?
A good ongoing accounting relationship makes this conversation more grounded. Your advisor can compare the proposal with the business's actual history, challenge an optimistic collection assumption, identify a missing cost, and help you understand the tradeoffs. You still make the business decision, with a clearer picture of what you are committing to.
At Woodard & Associates CPA, we help business owners bring financial reporting, business advisory, and tax planning into important decisions. If you are considering a major hire, purchase, or expansion, bring us into the conversation while you still have options on timing and scope.
Evaluating one decision also creates a foundation for the next stage: looking ahead regularly, before a major commitment becomes urgent. That is the focus of the final article in Your Business Numbers, From Looking Back to Planning Ahead.
This article is educational and is not individualized accounting, tax, legal, investment, or financing advice. Decisions should be evaluated with advisors who understand your business and circumstances.